Second Homes in South India: Why Investors Are Suddenly Comparing Coorg, Ooty and Munnar
Second homes in South India are having a moment. For years, the second-home conversation in India revolved almost entirely around Goa and the Himachal hill belt. That’s shifting. Institutional data, buyer-behaviour research, and on-ground listings all point to the same three names coming up together for the first time: Coorg, Ooty, and Munnar.
If you’ve been following our coverage of rental income potential across India’s top second-home locations, this South Indian cluster is the next logical comparison — and the numbers behind it are genuinely new, not recycled hill-station enthusiasm.
What’s Actually Driving the Second Homes in South India Trend
The clearest signal comes from institutional money, not retail chatter. According to Colliers India’s H1 2026 institutional investment report, Tier-II and Tier-III markets — Coorg among them — saw growing investor interest across hospitality, industrial, and residential developments during the first half of the year, part of a broader 70% year-on-year jump in institutional real estate flows into India. That’s a meaningful shift: Coorg isn’t just showing up in travel blogs anymore, it’s showing up in the same investment reports that track Chennai and Bengaluru.
Coorg: The Coffee-Estate Advantage
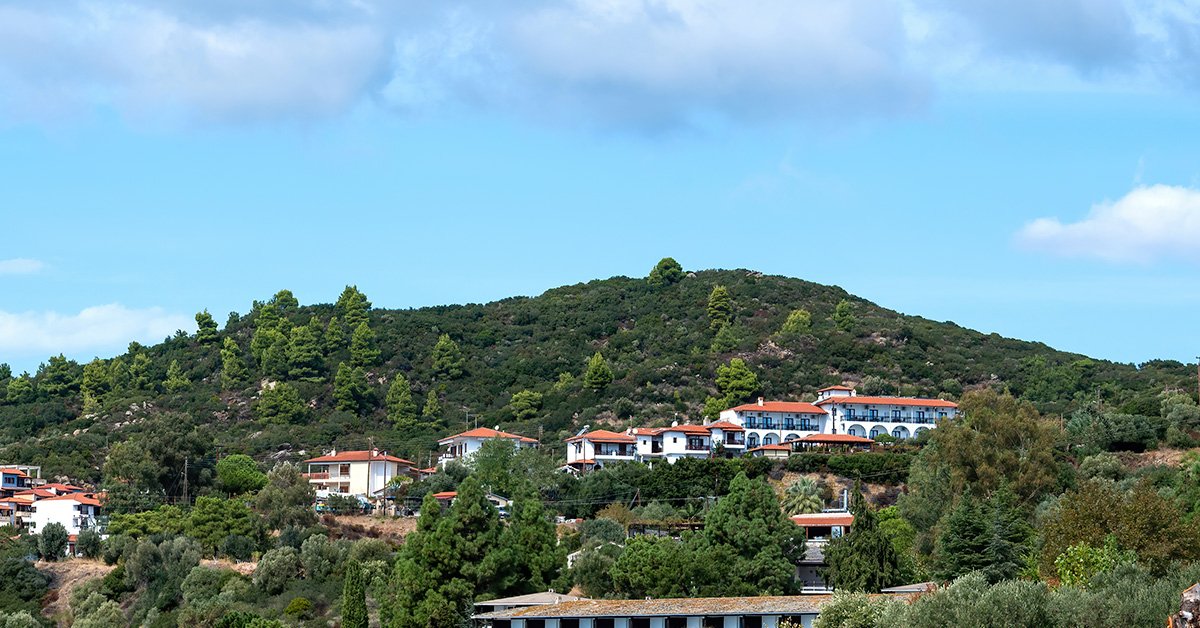
Coorg is where the second homes in South India story currently has the most institutional backing. Its eco-sensitive status limits new construction, which creates a natural supply ceiling — and with over 4.3 million tourists visiting annually, demand for homestays and vacation properties consistently outpaces available inventory. Market data from holiday-home platforms shows Coorg properties currently running rental yields around 6.5%, with capital appreciation trending near 6-7.5% annually. Coffee-estate villas and farmhouses have become a distinct product category here, separate from the branded-apartment developments common elsewhere.
Ooty and Coonoor: Established but Still Moving
Ooty and neighbouring Coonoor occupy a different tier — more established, more infrastructure, and correspondingly wider price bands. Property values in Ooty currently range roughly ₹3,260 to ₹15,000 per square foot depending on location, with Coonoor spanning a similar ₹2,777 to ₹16,666 range. Rental yields here sit in the more modest 4-6%territory, reflecting a market that’s matured past its early-growth phase but still draws steady wellness and retirement-driven demand.
Munnar: The Quiet Entrant
Munnar is the newest name in this comparison, and it’s arriving from a different angle — tea-country land value, eco-tourism growth, and a still-underdeveloped short-term rental market. Recent regional data shows Munnar’s Airbnb-style listings have grown nearly 79% year-on-year, even as the market remains small enough to be called boutique. That combination — fast supply growth, limited existing inventory — is exactly the setup that tends to precede a broader real estate repricing.
Why Investors Are Comparing All Three Together
What makes this a genuine trend rather than three unrelated stories is that these three destinations are now being evaluated by the same buyer pool, with all three names sitting inside the same second homes in South India conversation for the first time. Recent buyer-behaviour research on where India’s high-net-worth individuals are actually purchasing second homes in 2026 names Madikeri (Coorg), Coonoor, and Ooty together as an emerging “South Hill Belt,” distinct from the Nilgiris’ older money and Coorg’s newer coffee-estate appeal. Munnar is following the same script Coorg walked a few years ago — under-the-radar, agriculturally rooted, and increasingly attractive to buyers priced out of costlier hill markets.
What This Means If You’re Evaluating Second Homes in South India
The practical takeaway is that second homes in South India are no longer a single-destination decision — they’re a genuine three-way comparison, much like the Shimla-Chail-Kufri conversation already familiar to Himachal buyers. Coorg suits investors chasing yield and scarcity value. Ooty and Coonoor suit buyers who want established infrastructure and don’t mind lower rental returns. Munnar suits early movers comfortable with a market that’s still finding its footing.
The Co-Ownership Layer
As these markets attract more attention, fractional and co-ownership structures are becoming a natural entry point for buyers who want exposure to a specific micro-market — say, a coffee-estate villa in Coorg — without the capital commitment of buying outright. Platforms like BRIKitt, which already operates in comparable hill destinations such as Chail and Kufri, reflect how this ownership model is expanding into exactly this kind of emerging South Indian market.
South India’s second-home race is still early. But when institutional reports and buyer surveys start naming the same three towns in the same breath, it’s usually a sign the window for straightforward entry pricing is narrowing.